

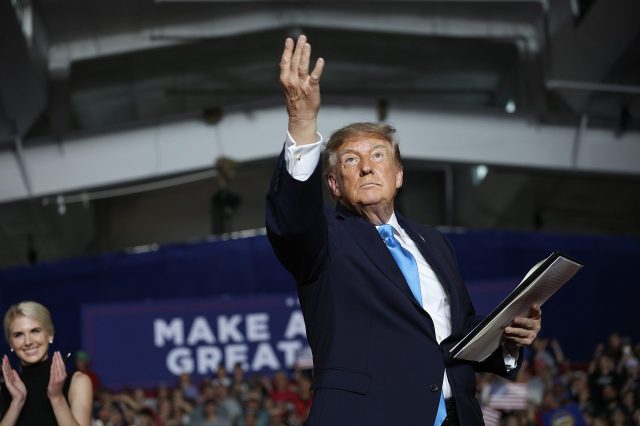
Trump signs an executive order to lower the cost of diesel during a campaign rally. (Win McNamee/Getty)


Nothing promotes economic growth more assuredly than cheap energy. Nothing dampens economic growth more comprehensively than high energy costs — and this is particularly true with regards to diesel fuel. Over 90% of freight in the UK moves by heavy-goods vehicle. Despite mandates to electrify the fleet, almost all these trucks still run on diesel. Diesel prices therefore impact everything you buy, and are critical to the construction, agriculture and manufacturing sectors. The 40% rise in UK diesel prices this year has increased inflation; slowed economic growth; and made interest-rate cuts much less likely. This painful price rise is a result of both current events and long-term, structural problems.
Diesel fuel trades in a global market. Gulf states usually provide 20% of this market, and Russia another 10%. Notwithstanding Donald Trump’s new plan to suspend sanctions on diesel imports from the latter, both these supplies have been severely disrupted. Yes, crude oil is now leaving the Gulf via pipelines, while a shuttle system of state-owned vessels, protected by the US Navy, ensures volumes very close to their pre-war level.
But shipments of refined products and petrochemicals have not recovered. Ukrainian drone attacks have damaged several Russian refineries, perhaps also explaining Trump’s rising anger with President Zelensky, whatever the truth of this latest “energy ceasefire”. China, for its part, has also prohibited the export of refined products in an effort to control domestic prices. Little wonder the rest of the world’s refineries are hard-pressed to meet demand. First of all, there are simply fewer refineries. In 2000, Britain had 18 refineries. Today it has four. Many of the closed refineries were too small to compete internationally, but high industrial electricity costs and environmental regulations also helped make them uneconomic.
Second, a barrel of crude oil contains a variety of molecules that refineries break down into different products: based primarily on their boiling points. Gasoline is a light distillate with a low boiling point. Diesel and jet fuel are middle distillates with higher boiling points, while marine bunker fuel is a heavy distillate. Most refineries are built to process specific types of crude and produce a specific mix of fuels. Separating the different segments of a barrel of crude oil is a complex process; refineries cannot always adjust quickly, even if demand shifts from one product to another.
Another factor is the shipping industry, which uses 4% of global oil production. In 2020, the United Nations’ International Marine Organisation dramatically shifted global energy demand, when it compelled the world’s ship owners to stop using heavy marine bunker fuel, and start burning more environmentally friendly fuels like marine gas oil. Unfortunately, marine gas oil comes from the same segment of the crude barrel as diesel and jet fuel. While the impact of this change was initially masked by Covid, which reduced oil demand, this has permanently increased demand for middle distillates. That, in turn, has raised the cost of all shipping, flying and heavy goods transport, and made diesel and jet-fuel prices more volatile.
Britain now produces only half of the roughly 500,000 barrels of diesel it consumes every day. The rest is imported. Since Russian supplies were suspended in 2022, most of those imports come from the US, Belgium, the Netherlands and the Middle East. All over the world, refineries that can produce diesel and jet fuel are operating at maximum capacity. In the US, capacity utilisation has reached 98%, the highest utilisation rate in a quarter of a century. The “crack spread”, which measures the difference between what a refinery pays for crude and what it sells product for, is now three times its historic average. If refineries could produce more diesel, they surely would.
The headline-grabbing news in the UK has been £2-a-litre diesel. However, the fuel’s retail price has actually risen by less than the price of crude oil. Dated Brent crude is up 70% this year, while the price of diesel has risen by only 40%. This is largely because, in the UK, two fifths of the price of diesel is tax: which does not vary with the price of crude. Moreover, dated Brent is a spot price that changes with the latest news, while refineries producing diesel operate on more stable long term contracts.
Things look very different in America. The United States is the world’s largest oil producer, and its largest diesel exporter. Most of those exports go to Latin America, not Britain. Nevertheless, diesel fuel prices in the US have risen by nearly 80%, compared with only 40% in the UK. In fact, while retail diesel prices in the UK have risen by a smaller percentage than the price of Brent crude, in the US the opposite is true.
With diesel prices reaching the equivalent of $200 per barrel in the US, and crucial midterms coming up, the Trump administration had ample motivation to act. America is exporting 30% of its diesel production into a global market. At the same time, America’s own strategic petroleum reserve is at its lowest level in 44 years. Between 2021 and 2025, the Biden administration drew down America’s reserve by 45% — or 245 million barrels — largely following the Russian invasion of Ukraine. During that same period, all the other G7 nations together drew down their own reserves by only 40 million barrels. In other words, the US government provided the global market with 85% of the oil used to calm markets after the Russian invasion.
Always a proponent of America first, President Trump concluded that other nations should now draw down their own stocks, rather than continue to rely on American reserves. Trump’s threat to ban US diesel exports has anyway been effective, resulting in a commitment by other G7 members to release 100 million barrels of oil over just four months. As a result of this agreement, diesel prices in both Europe and the United States have declined slightly. For his part, Trump has also signed an executive order granting fuel tax breaks, usually reserved for farmers, to truckers. This latest diesel-exporting agreement with Russia — while mattering more from a geopolitical perspective — is also perhaps intended to help drivers at the pump.
Whether any of this will bring down prices enough to benefit Republican election prospects next month remains to be seen. What may be more long-lasting is the damage done to public opinion on both sides of the Atlantic. Americans increasingly view European governments as freeriders: unwilling to meet their Nato defence commitments, but quite happy to use America’s strategic petroleum reserve and diesel exports to keep their own fuel prices down. As for the Europeans, they see a transactional Trump administration extorting its allies for domestic political purposes. Both sides have a point. Either way, the old political adage remains true: if loyalty is a sentiment, leverage is a fact.