


Nov 10 2026 - 1:30pm
It’s never a great idea, but right now is definitely not the time for a major architect of America’s AI boom to get caught sleeping with the enemy.
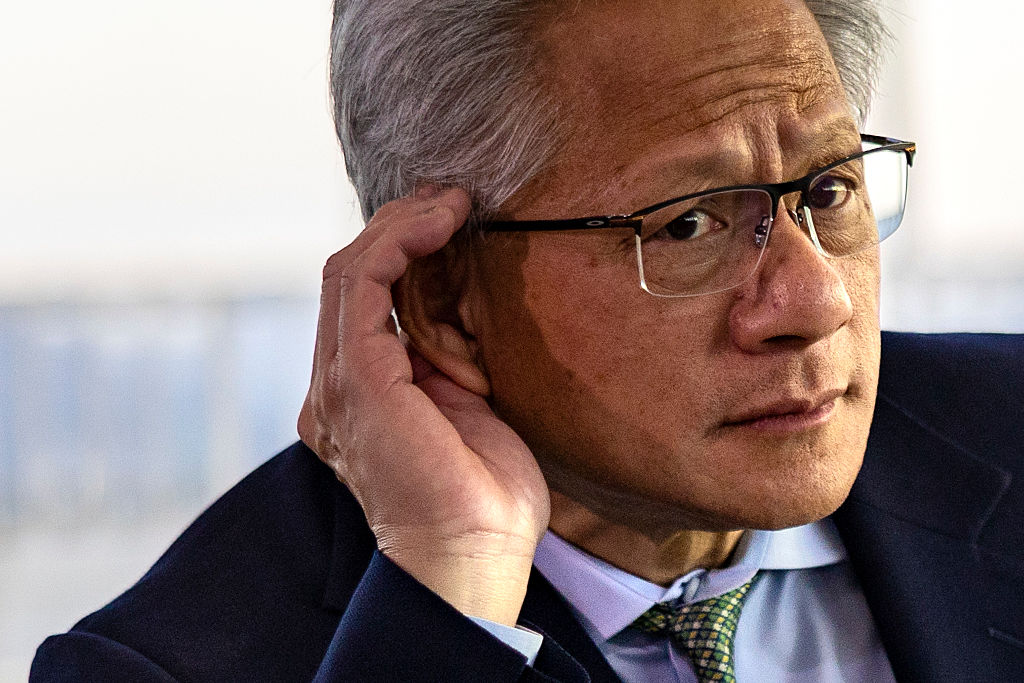
But here we are. It emerged this week that Nvidia CEO Jensen Huang, whose firm is the chipmaker at the heart of the US’s massive data-center buildout, had an affair with a woman who US intelligence believes was recruited as a Chinese spy. What makes this case worthy of Hollywood is that Huang has been one of the loudest exponents of closer ties with China. His proximity to President Donald Trump therefore raises questions about whether he got an easy ride, not least because concerns about the security risks involved had been raised within the administration. There’s no doubt the incoming Congress will be keen to interrogate the Nvidia boss.
After years of looking unstoppable, the AI boom has entered a vulnerable phase. With the cost of the debt being used by hyperscalers to keep building going up, investors had begun demanding harder answers from AI executives and were punishing any firms whose earnings failed to keep pace with their spending. Then there’s the vulnerability that the AI ecosystem is a tight, almost incestuous web of firms which serve as each other’s customers and investors. Nvidia itself has been a key investor in many of its customers, having plowed nearly $100 billion into the companies that buy its chips, thereby enabling them to keep doing so.
Therefore, if one of the key cells in this web encounters difficulties, it raises the risk of contagion. Considering the degree to which rising share prices have bolstered earnings in the sector and boosted the collateral they have been able to use to raise loan money, they have managed to keep inflating the bubble. Anything which interrupts that gravy train could derail the whole boom.
Monday’s strong rally in US stocks gave the impression that the worst had passed, and that the brutal sell-off in AI shares which climaxed after the midterms had run its course. In fact, the bounceback was misleading: it reflected not a recovery in AI stocks but the continuation of a trend that had begun weeks earlier. That is, the rotation out of AI stocks and into the shares of so-called “defensive” sectors such as consumer products and healthcare. Given that those are the sectors investors pile into when they anticipate a possible recession, Monday’s rally was, if anything, ominous.
Meanwhile, the AI bubble has been the key driver of the US stock market, which has in turn become a key driver of the economy. As share prices rose, the positive wealth effect among richer Americans provided a key source of income for expanded consumption, which helped keep the economy turning over strongly. But after years of double-digit rises, the rally ran out of steam earlier this year, and the market is currently trading where it was last spring.
Should that stagnation continue — or, worse, should the stock market fall — the positive wealth effect will disappear. Given that real wages for most workers are currently declining, due to the surge in inflation, a weakening of consumption among the richer half of the economy could lead to a rapid slowdown. That, in turn, could create a vicious and self-reinforcing spiral in the stock market and the economy.
In short, this is one mess the Nvidia board will want to sort out in a hurry. The problem is that Huang may be too big to fire.
John Rapley is an author and academic who divides his time between London, Johannesburg and Ottawa. His books include Why Empires Fall: Rome, America and the Future of the West (with Peter Heather, Penguin, 2023) and Twilight of the Money Gods: Economics as a Religion (Simon & Schuster, 2017).
 jarapley