


October 2 2026 - 6:00pm
Today, Donald Trump announced in a Truth Social post that “Europe has just agreed to release a massive amount of their heavily stocked Diesel Oil. The process will begin immediately.” The White House had placed European countries including the UK under pressure to release 120 million barrels of diesel from their strategic reserves. Member states of the International Energy Agency (IEA) that are net oil importers, like many of those in Europe, are required to hold stocks of fuel equivalent to 90 days of imports in reserve. However, the Trump administration insisted that some of that stock be released onto the markets to bring down prices.
An alternative, the White House stated, would have been for the US to cease exports of diesel to Europe, to reduce the pressure on prices for American consumers. It is not clear how much the UK would be expected to contribute to that release. However, almost any outcome from these discussions is likely to result in turbulence in the UK diesel market, due to the country’s severe vulnerability to supply-chain disruption.
The root of this issue is Europe’s dependence on imports of diesel, using far more than it produces. Over the course of the Nineties and 2000s, EU directives and domestic environmental rules encouraged a switch to diesel, skewing the demand ratio of gasoline and diesel. But Europe already had a well-developed fleet of refineries which were geared primarily towards gasoline production. High taxes and additional environmental regulations never made it appealing for investors to put in the money to upgrade the refineries for increased diesel output.
In the UK, this trend has been exacerbated by the general depletion of refining capacity overall. No new refinery has been built in Britain since the 1973 oil shock, and capacity began to fall off as plants aged. In recent years, plants have rapidly closed as high energy prices and carbon taxes in Britain have caused refineries to close. Teesside closed in 2009, followed by Coryton and North Tees in 2012, and Grangemouth and Lindsay last year. The UK’s total refining capacity has fallen by about half since 2000. While the country is a net exporter of gasoline, the majority of diesel is now imported.
Instead, Britain buys diesel from the US and the European hub in Rotterdam. Some of the product from Rotterdam was refined locally but the loss of Russia and, increasingly, the Gulf as a source has massively depleted supply. Losing American supplies would be a massive blow to Europe. But the fact that the White House is now pushing for a deal suggests that the Trump administration is looking to avoid going down that route.
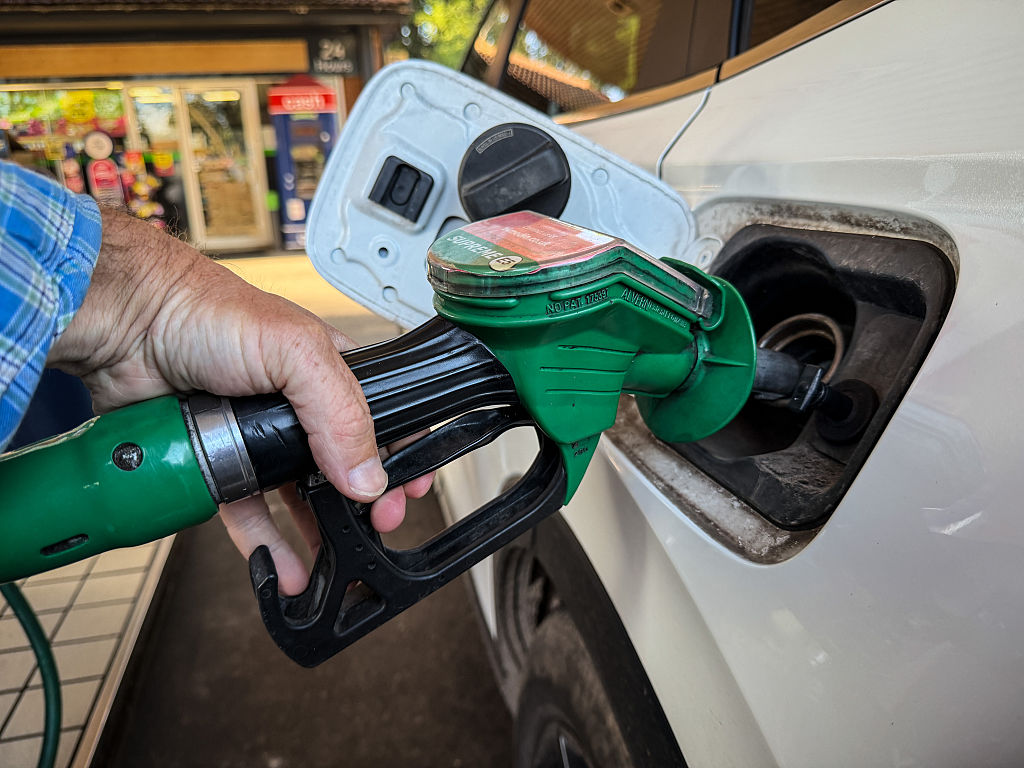
A general release of storage onto the markets now might provide brief relief at the pumps for British consumers. However, it signals the risk of potential shortages over the winter if imports remain too low, which would push prices back up. The Government holds no strategic reserve of fuel itself, having transferred its IEA obligations onto private companies since the Eighties. British companies hold about 10 million tonnes of reserves of all types of oil, but only a few weeks’ consumption of diesel as a product category. By way of comparison, France has a strategic reserve of seven million tonnes of diesel alone.
The British press often refers to “42 days’ emergency diesel”, but this figure is hardly accurate, and doesn’t refer to a real physical stockpile. Instead, a reasonable estimate is that there are around two million tonnes of road diesel in reserve. What’s more, it is likely that about a fifth of this is not in the UK at all, but is instead sitting in those companies’ tanks on the continent, raising questions about what happens in the case of emergency export bans.
Yet again, British consumers face high costs and uncertainty as a result of a chronic lack of strategic resilience. The Government decided to exit the energy infrastructure sector, believing it was better left in private hands, but then created a regulatory environment in which investors didn’t want to do the job either.
Chris Bayliss is an independent consultant who works on energy infrastructure in the Middle East.
 baylissbaghdad